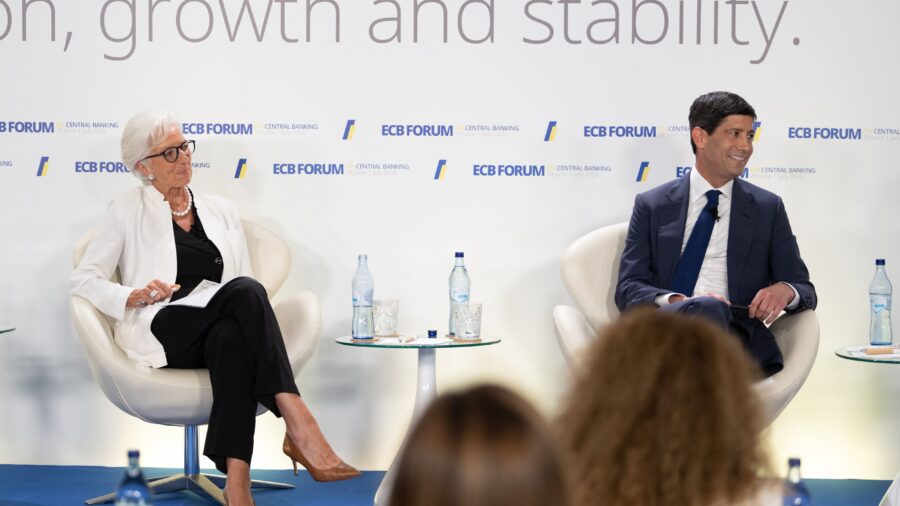
Central banks in the United States and the Eurozone are convening this week to address a complex economic landscape defined by persistent inflation, rising risk premiums, and fluctuating oil prices. Market analysts anticipate that policymakers will maintain current interest rates, with potential adjustments deferred until December.
The Current Economic Environment
Financial authorities are navigating a convergence of traditional monetary policy and broader political developments on both sides of the Atlantic. While economic indicators such as inflation and artificial intelligence impacts remain central to the discussions, the influence of political factors has become increasingly prominent. Investors and economists are prioritizing the rhetoric and guidance provided by central bank officials over immediate statistical data, as the intersection of monetary strategy and political climate complicates the decision-making process.
Looking Toward December
Despite the high volume of information impacting the current meetings, expectations for immediate changes to the cost of money remain low. Market consensus suggests that central banks will likely hold rates steady during these sessions. Observers are shifting their focus to the final quarter of the year, anticipating that potential shifts in monetary policy will materialize in December rather than in the immediate term.
Current Policy Outlook
Central banks remain in a holding pattern as they weigh geopolitical and economic variables. The upcoming guidance from these institutions will be critical in shaping market expectations for the remainder of the year.
Why it matters: The stability of global interest rates directly impacts international trade and capital flows. For emerging markets and the Middle East, the decisions made by the U.S. Federal Reserve and the European Central Bank influence currency valuations, debt servicing costs, and the overall cost of imported goods, making these policy meetings significant for global financial stability.
 Egypt
 Saudi Arabia
 UAE
 Spain
 United Kingdom
 United States
 China
 India