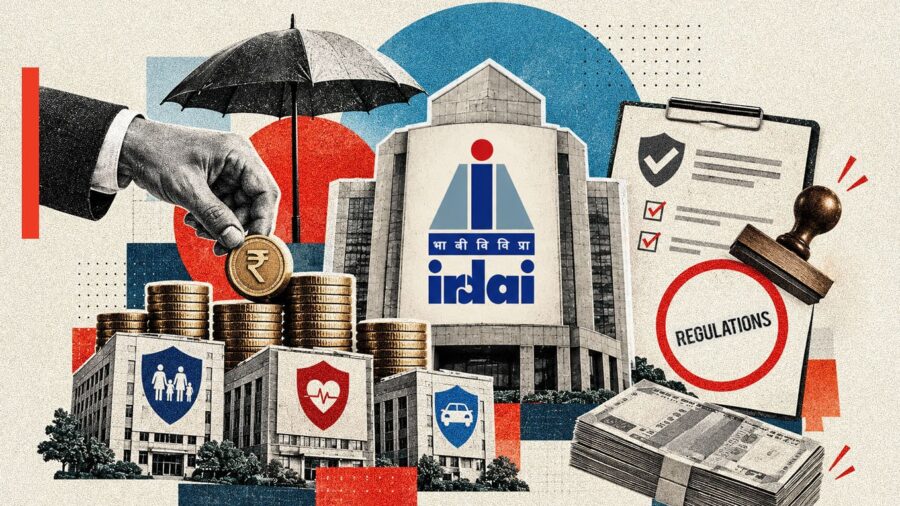
The Insurance Regulatory and Development Authority of India (IRDAI) has extended the deadline for stakeholders to provide feedback on proposed insurance distribution reforms. The new deadline is October 31, moving from the original date of October 25.
Key Takeaways
- Deadline extension: The regulator moved the submission date following an “encouraging response” to the consultation paper.
- Consultation volume: The IRDAI reports receiving more than 650 comments regarding the document, titled “Recalibrating Economics of Insurance Distribution.”
- Industry opposition: The Insurance Brokers Association of India (IBAI) previously requested an extension until December 31, citing concerns over proposed commission caps.
- Economic impact: The IBAI warned that the proposed norms could result in a 60-70% revenue decline for the broking sector and the potential loss of up to 1 million jobs.
- Regulatory objectives: The IRDAI aims to adjust commission structures and tighten insurer expense limits to address rising distribution costs.
Background on Proposed Reforms
The IRDAI released its consultation paper on September 23, proposing a reintroduction of product-wise commission caps for distributors. The regulator also suggested stricter limits on the total expenses insurers can incur, citing concerns over a disproportionate rise in commission payouts to distributors. According to IRDAI data, general insurance premiums sourced through brokers grew 37% between fiscal years 2023 and 2027, while commission payouts increased by 173%.
Industry Response and Concerns
The IBAI has challenged the regulator’s data, arguing that the rise in commissions since fiscal year 2023 reflects the reclassification of off-book marketing expenses rather than inflationary pressure on consumers. The association maintains that the entire general insurance industry’s operating expenses average approximately 26.5% of gross premiums, which remains within the existing 30% limit.
 Egypt
 Saudi Arabia
 UAE
 Spain
 United Kingdom
 United States
 China
 India