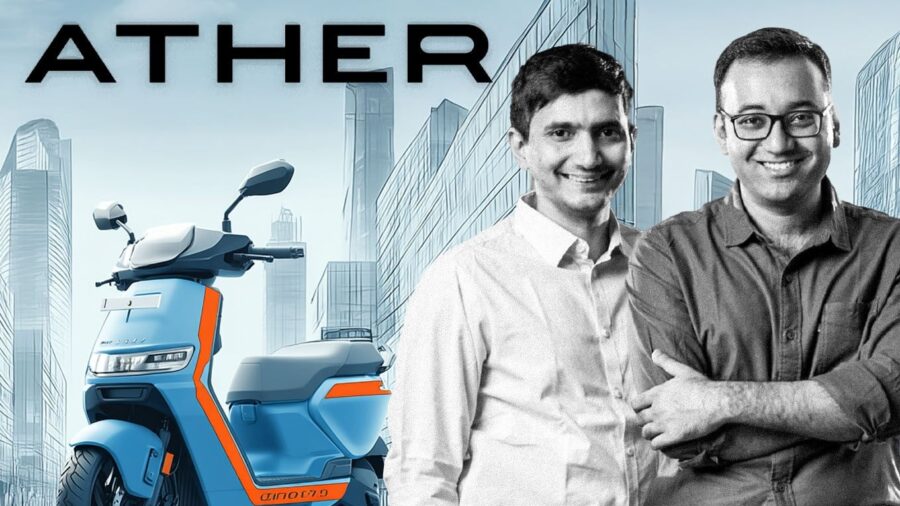
Ather Energy shares rose 8.1% to an intraday high of ₹1,702 on the BSE on Wednesday following upward price target revisions from HSBC and Nomura. The gains follow the electric two-wheeler manufacturer’s second-quarter fiscal year 2027 earnings report, which showed the company achieving its first profitable quarter.
Analyst Revisions and Q2 Performance
HSBC and Nomura maintained ‘Buy’ ratings for the stock, citing better-than-expected margins and positive growth projections tied to the new Konarc scooter range. HSBC increased its price target to ₹1,800 from ₹1,600, noting that Ather achieved EBITDA breakeven sooner than anticipated despite commodity cost pressures.
Nomura raised its target to ₹2,070 from ₹1,926. The brokerage highlighted that Ather’s EBITDA margin, excluding other income, reached 0.8%, surpassing consensus estimates of negative 2.7%. The company reported a consolidated net profit of ₹1.3 crore for the quarter, compared to a loss of ₹154.1 crore in the same period last year. Operating revenue grew 62.9% year-on-year to ₹1,464.2 crore.
Expansion and Future Outlook
Ather announced plans to invest ₹122 crore to increase manufacturing capacity at its Hosur plant in Tamil Nadu and its upcoming Factory 3.0 in Maharashtra. The investment aims to add 2.25 lakh units of annual production capacity.
CEO Tarun Mehta stated during an earnings call that the company intends to prioritize sales growth and capacity expansion over immediate net profitability. He noted that recent margin improvements were partially driven by temporary factors, such as adjustments to product mix and changes in incentive structures.
Why it matters: This development highlights the improving financial viability of India’s electric vehicle sector. As companies like Ather move toward profitability, increased manufacturing capacity and positive analyst sentiment suggest a scaling industry that could influence global supply chain trends and investment interest in emerging markets.
 Egypt
 Saudi Arabia
 UAE
 Spain
 United Kingdom
 United States
 China
 India