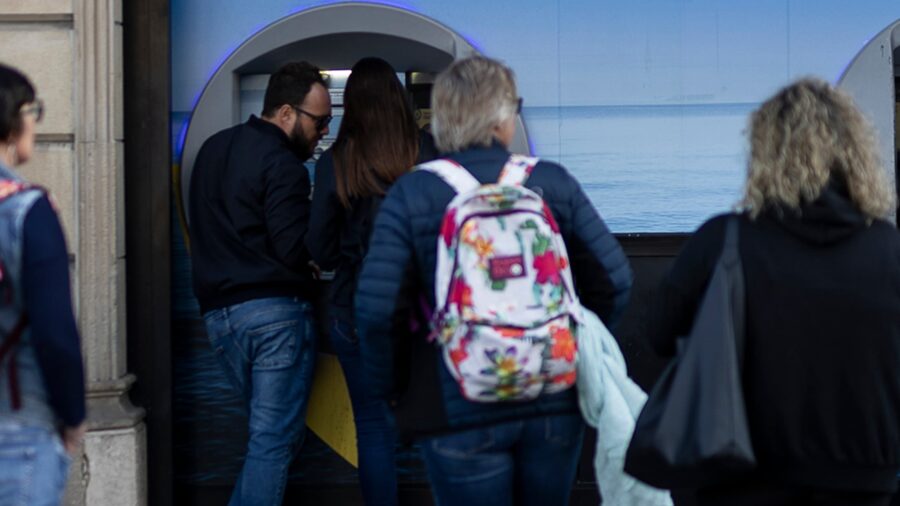
Spanish banks may charge as much as €276 a year for maintaining a current account and debit card for customers who do not meet fee‑waiver conditions.
The fee represents the highest amount among eleven banks examined for a client who fails to satisfy any of the contractual requirements that would exempt them from charges. The analysis focused on customers with minimal engagement, such as infrequent transactions or low balances.
Fee structure and comparison
All banks surveyed apply a tiered fee system that rewards higher usage or linked products, such as mortgages, savings plans, or regular salary deposits. Customers who lack these ties are classified as “non‑linked” and subject to the full maintenance charge.
Among the eleven institutions, the top fee of €276 per year was identified at a major Spanish bank. Other banks charged lower amounts, but the range varied widely depending on the specific criteria each bank uses to define a linked customer.
Implications for consumers
Consumers with dormant or rarely used accounts risk paying the full fee unless they actively link additional services. Financial advisers recommend reviewing account terms regularly and consolidating banking relationships to avoid unnecessary costs.
Regulators have not indicated plans to standardise fee disclosures, leaving customers to rely on bank‑provided information at account opening.
Why it matters: The high annual charge can erode savings for low‑income households and students in Spain and the broader Middle East, where many maintain basic accounts abroad. Understanding fee structures helps consumers avoid unexpected expenses and make informed banking choices.
 Egypt
 Saudi Arabia
 UAE
 Spain
 United Kingdom
 United States
 China
 India